Newton-Cotes Framework
The Newton-Cotes formulas provide a systematic way to approximate a definite integral by replacing the integrand with a polynomial that passes through a set of equally spaced nodes. Because polynomials integrate exactly and in closed form, this replacement converts the original integral into a weighted sum of function values that is easy to compute.
The Core Idea
We want to evaluate:
Instead of integrating directly, we approximate it with the degree- Lagrange interpolating polynomial built from equally spaced nodes on , and integrate that polynomial:
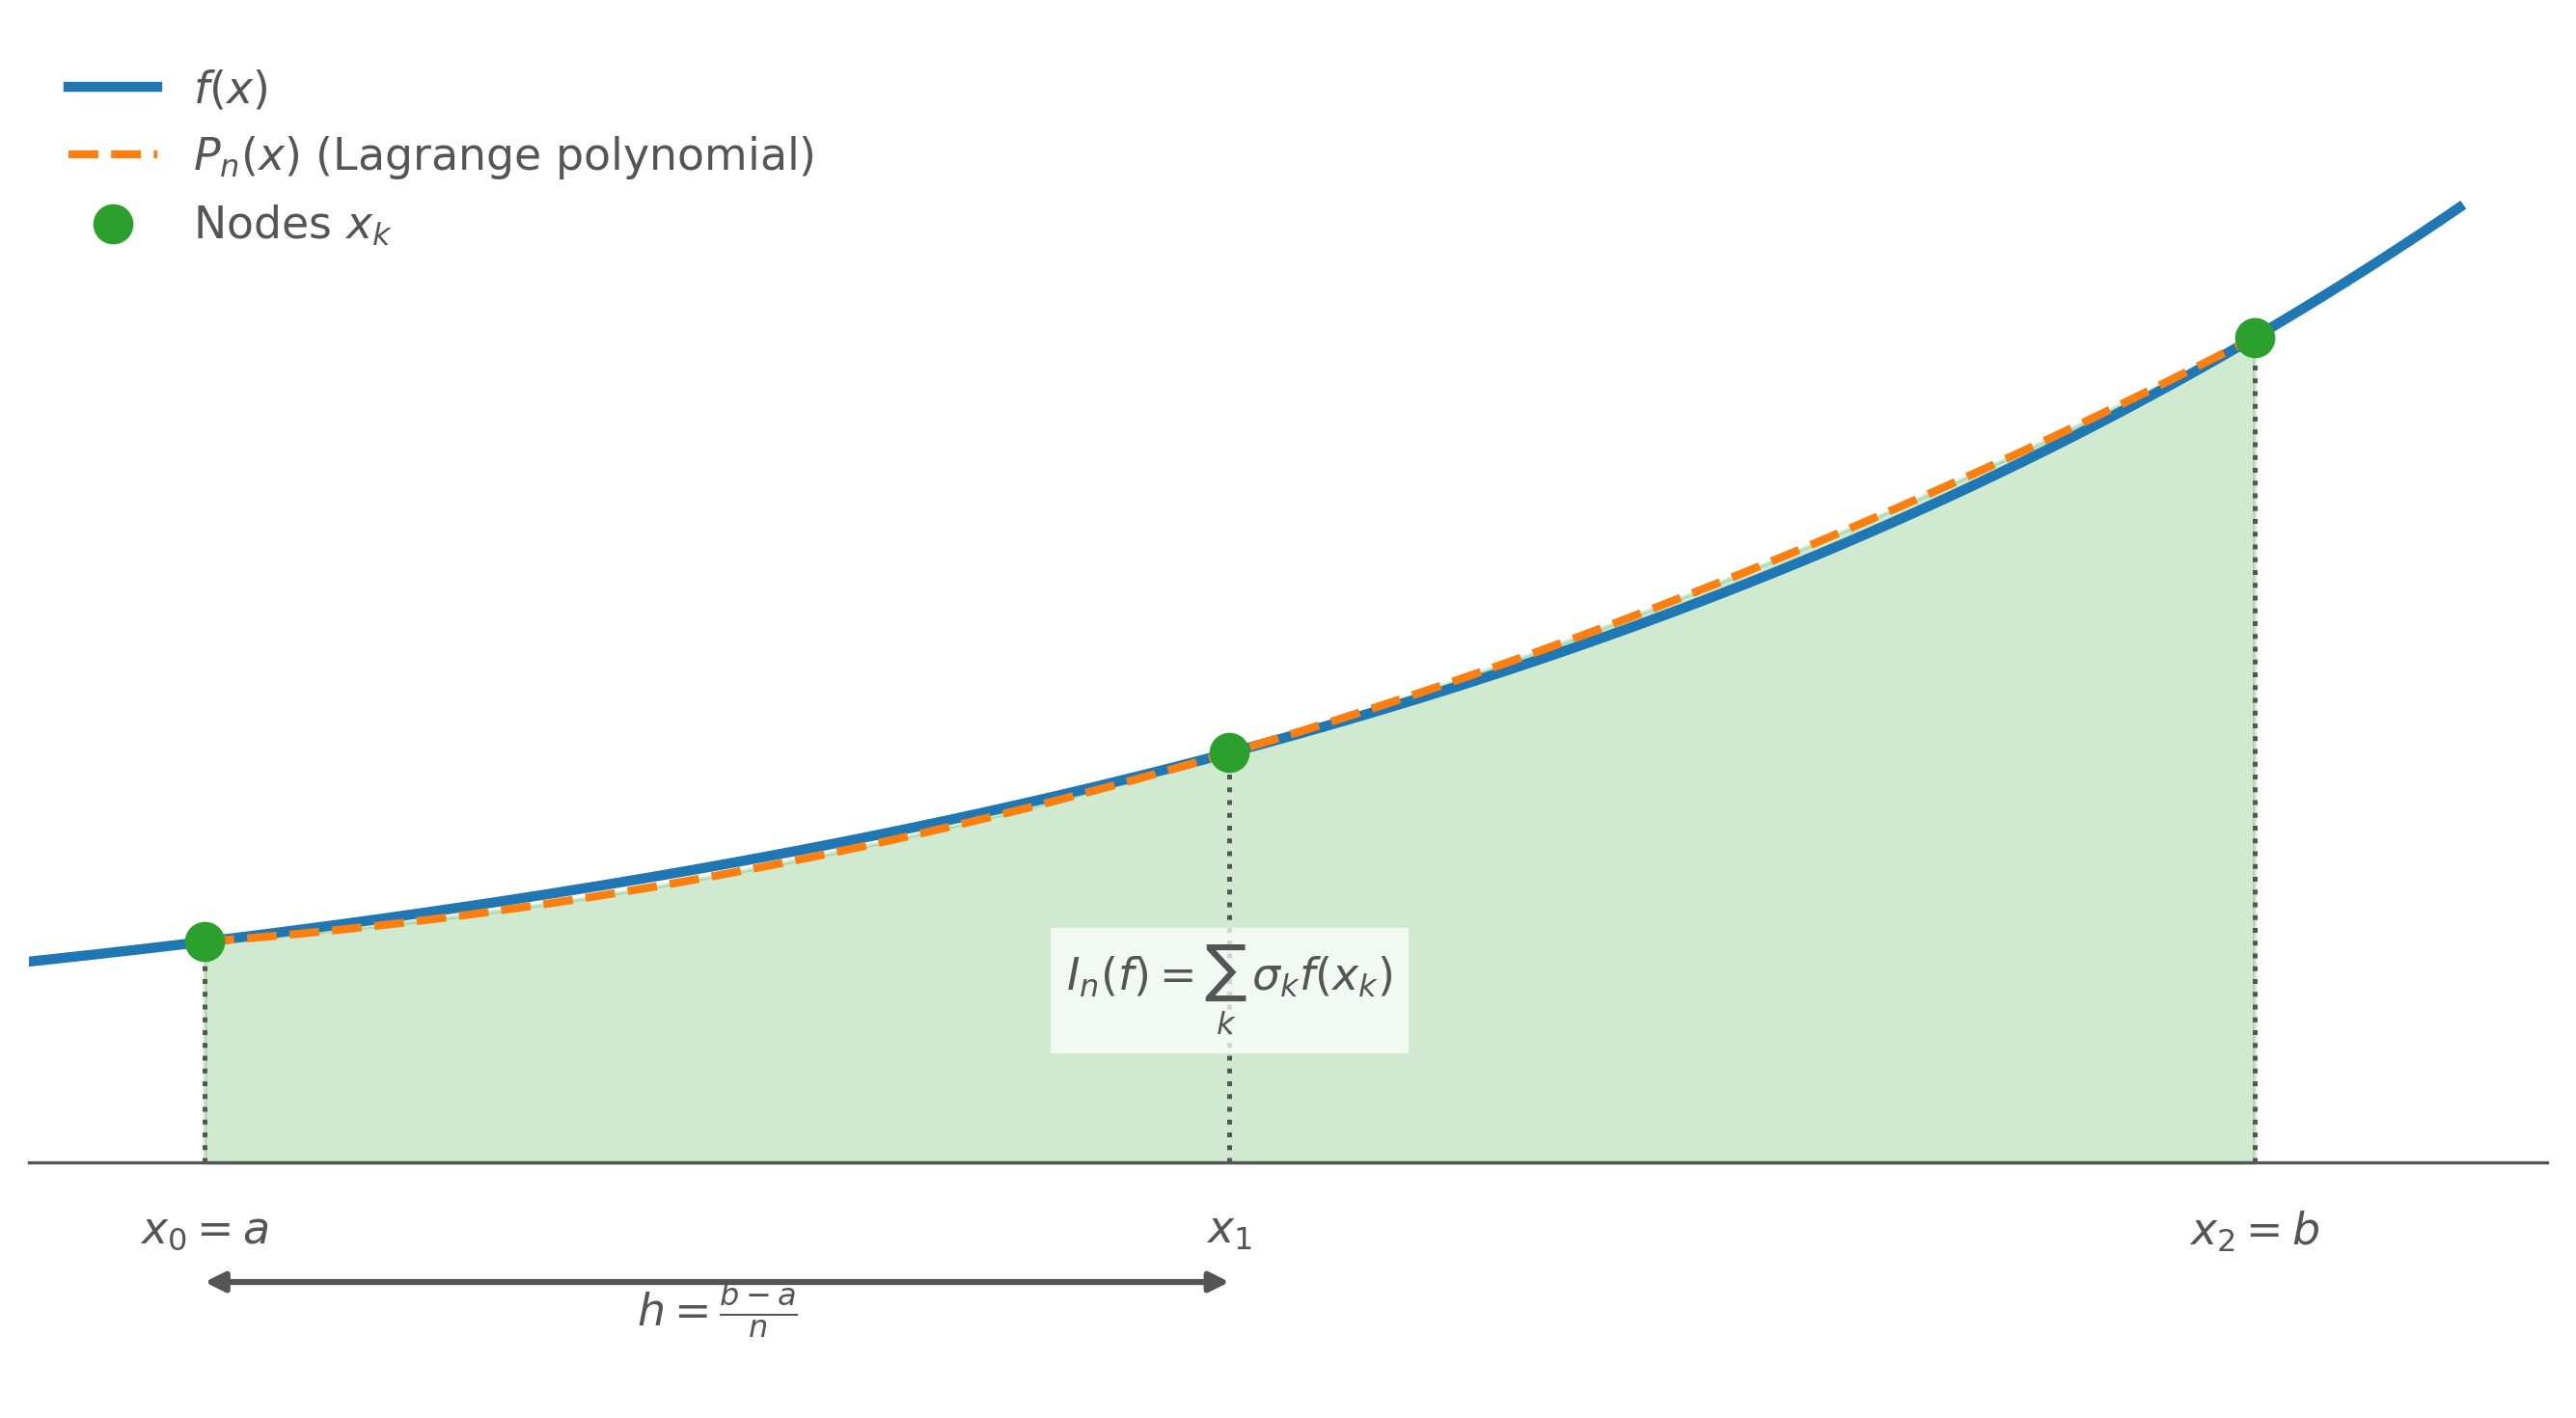
The shaded region is the integral of , and its value equals the weighted sum where each weight is the integral of the corresponding Lagrange basis polynomial .
Deriving the Weighted Sum
The Lagrange interpolating polynomial can be written as:
where each is the -th Lagrange basis polynomial. Substituting into the integral:
Since the function values are constants with respect to , they can be pulled outside each integral:
This gives us the fundamental Newton-Cotes formula:
where the Newton-Cotes weights are defined as:
Each weight depends only on the positions of the nodes, not on the function values. This means the weights can be computed once and reused for any function on the same interval.
Closed and Open Forms
Newton-Cotes formulas come in two variants depending on whether the endpoints and are used as nodes.
Closed Newton-Cotes
The closed form includes both endpoints as nodes. With nodes (including and ), the step size between consecutive nodes is:
The nodes are:
so that and . The two most commonly used closed formulas are:
| Rule | Number of nodes | |
|---|---|---|
| 1 | Trapezoidal Rule | 2 |
| 2 | Simpson’s Rule | 3 |
Open Newton-Cotes
The open form excludes both endpoints. The interior nodes are shifted inward by one step from each endpoint, giving a step size of:
The nodes are:
Open formulas are useful when cannot be evaluated at the endpoints, for example when or is undefined.
Summary
The entire Newton-Cotes framework reduces to three steps:
- Choose equally spaced nodes on .
- Compute the weights for each node.
- Evaluate .
The next two sections carry out this programme in full for (Trapezoidal Rule) and (Simpson’s Rule).